Tesla’s third-quarter revenue was flat at about $28.05 billion, in line with analyst expectations, but profits fell sharply, with Electrek attributing the drop to spending on artificial intelligence and robotics, including the Optimus robot, growing faster than gross profit. The figures come from the electric-vehicle maker’s results, published on 21 October and summarised by the technology and EV news outlet Electrek.
According to Electrek, adjusted earnings per share were 48 cents, ahead of the 45-cent consensus but down 4% on a year earlier. Net income under US accounting rules was $787 million, down 43%. Operating income dropped 56% to $718 million, giving an operating margin of 2.6%, compared with 5.8% a year before.
Margins Recover, Spending Climbs
Total gross margin improved to 19.6% from 18.0% a year earlier, and automotive gross margin excluding regulatory credits reached 18.1%. Regulatory credit income was much smaller, at $113 million against $417 million a year earlier. Operating expenses rose 39% to $4.78 billion, with research and development up 69% to $2.76 billion. Capital expenditure was $4.73 billion, and free cash flow fell to $1.53 billion from $3.99 billion.
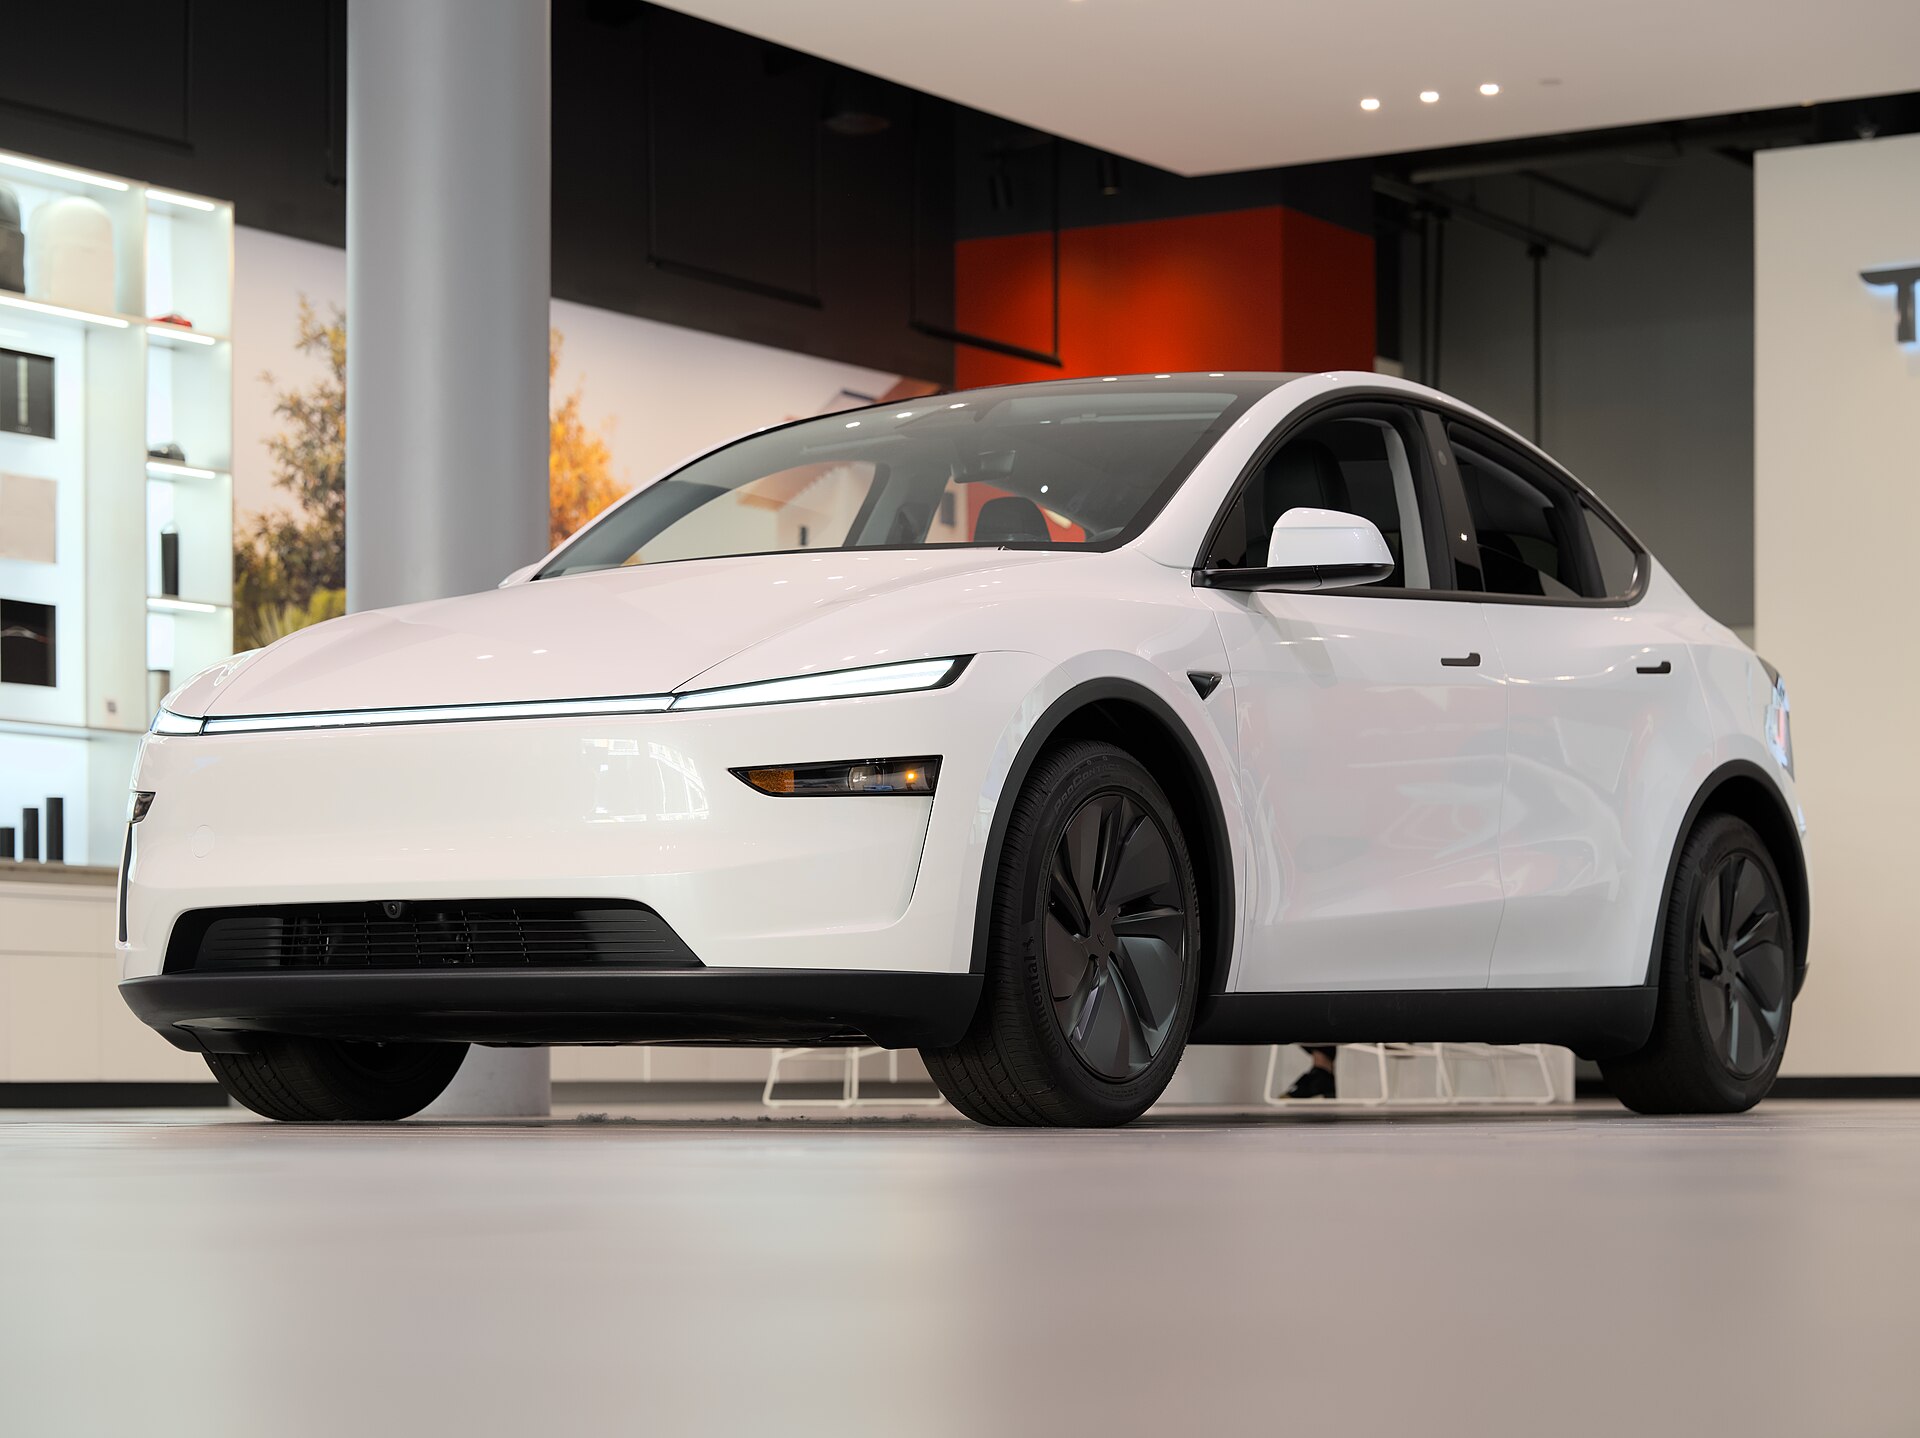
Tesla delivered 486,532 vehicles, down 2.1% year on year, while production was 464,391. Inventory fell to 11 days of supply from 15 in the second quarter. In its letter, Tesla said battery availability continued to limit vehicle volumes and cited the largest backlog for its passenger vehicles in four years.
Energy, Services and Autonomy
Energy generation and storage revenue declined 16% to $2.88 billion even though deployments rose 10% to 13.7 gigawatt-hours. Services and other revenue grew 33% to $4.61 billion. Electrek reported that active subscriptions to the company’s Full Self-Driving software reached 1.74 million, up 67%, and that its robotaxi operation had covered nearly two million cumulative unsupervised miles.
Management has guided to capital spending of more than $25 billion for 2026. Electrek noted that this implies a much heavier fourth quarter, and called the battery-supply explanation new, noting that falling average selling prices are unusual for a supply-constrained automaker, an interpretation it presented as its own analysis.
Why It Matters
Tesla is now being valued less as a carmaker and more as a bet on autonomy, robotics and energy, so the balance between today’s profits and tomorrow’s spending is the central question for investors. This quarter shows a business whose core vehicle margins are recovering while headline profit is squeezed by heavy investment. How quickly the company can turn robotaxis, subscriptions and storage into reliable earnings will shape both its own path and the wider competition among EV and technology groups.
Leave a Reply