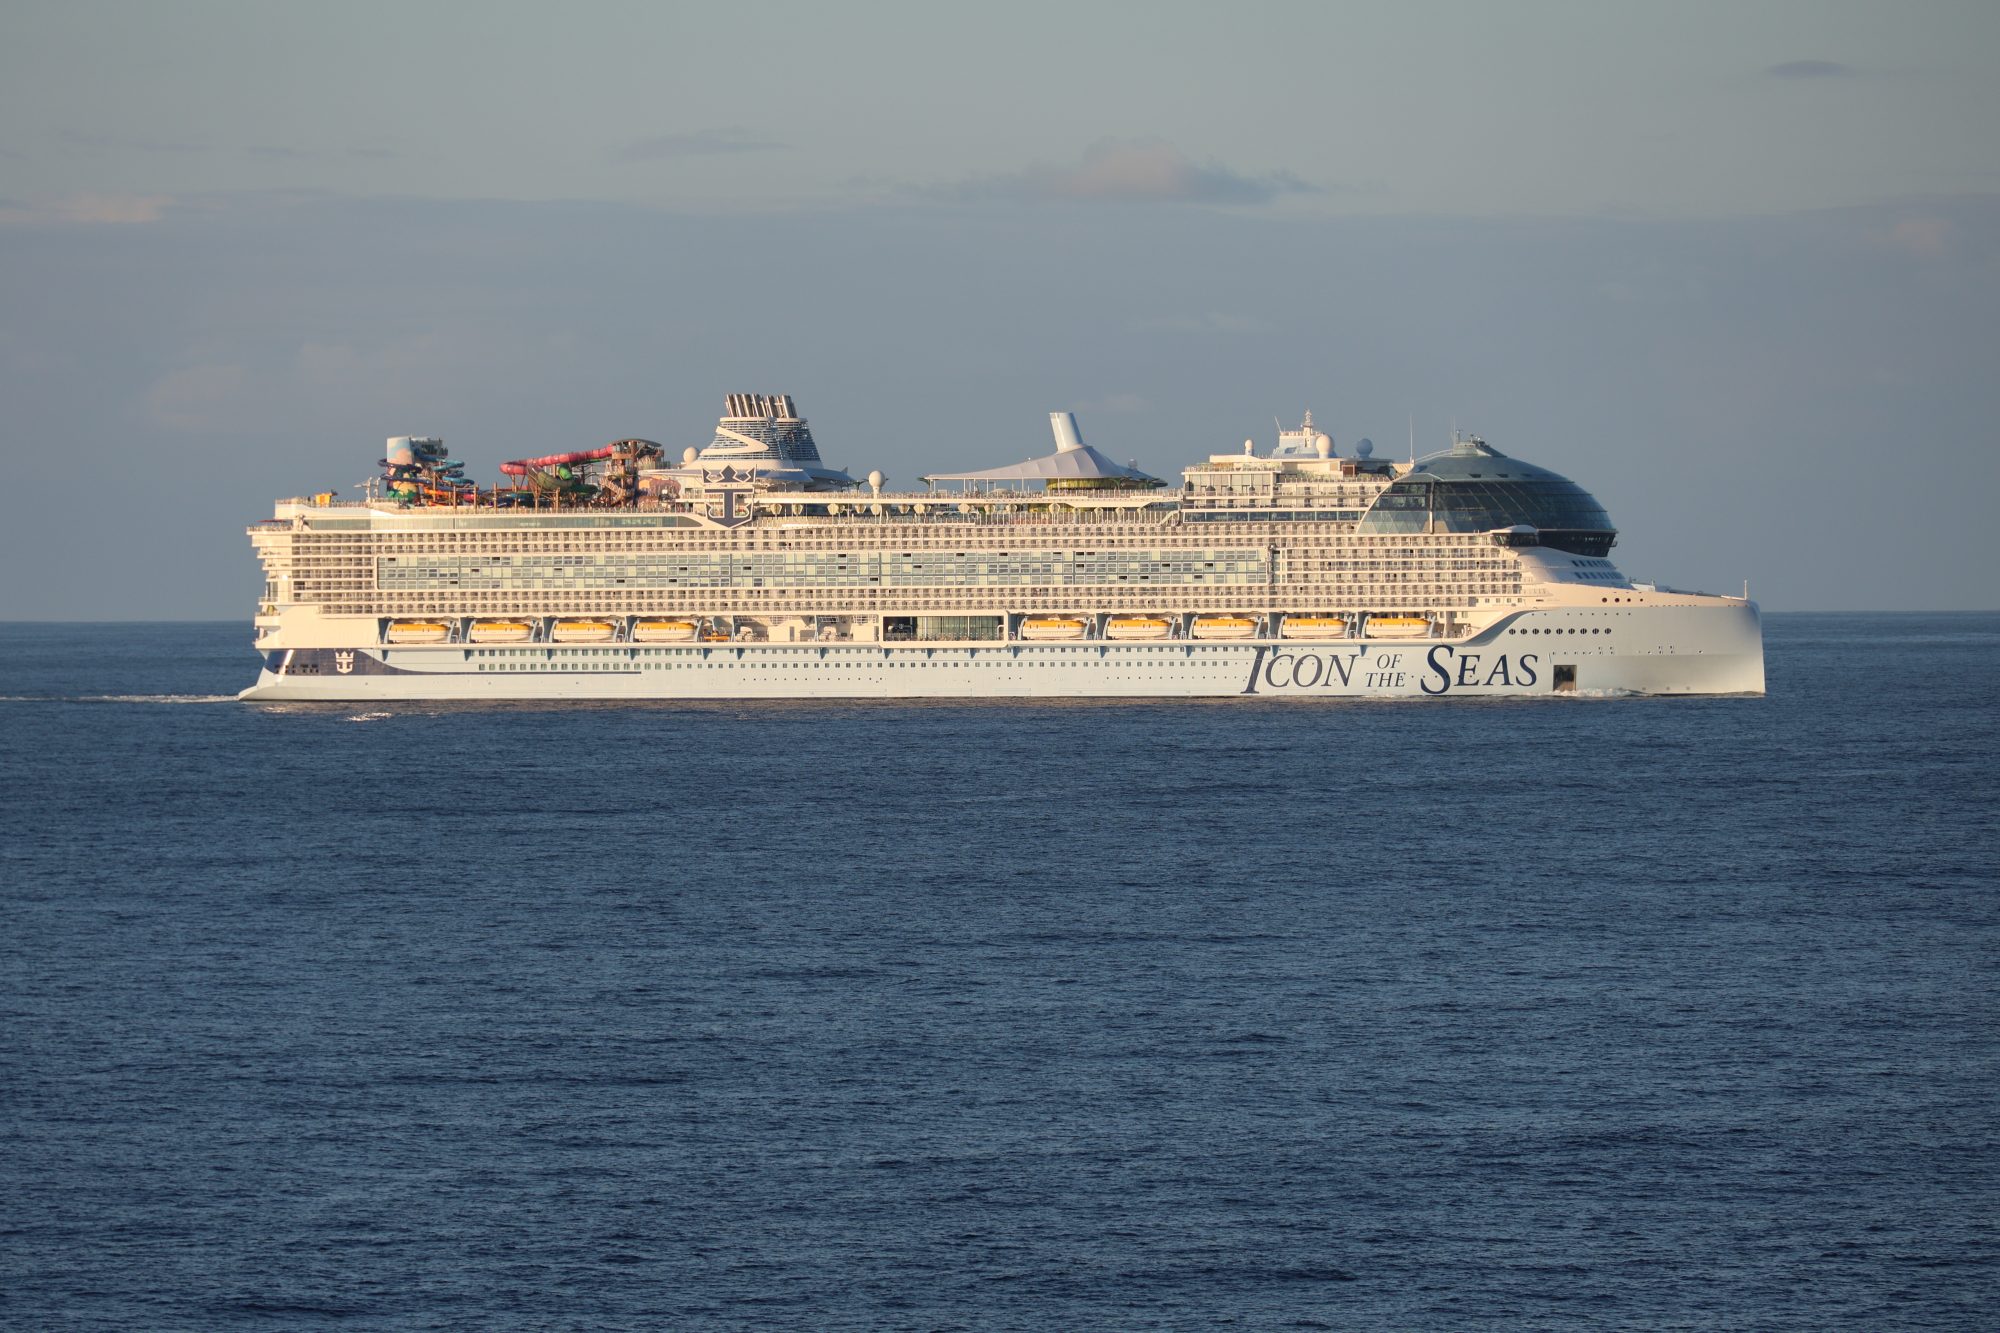
Royal Caribbean Group said on 27 October that it earned net income of $1.7 billion, or $6.45 per diluted share, in the third quarter of 2026, up from $1.6 billion, or $5.74 per share, in the same quarter of 2025. Total revenue was $5.6 billion, up 9% from $5.1 billion, according to the results release issued from Miami.
GAAP and Adjusted Figures
On an adjusted, non-GAAP basis, the company reported net income of $1.8 billion and earnings per share of $6.57, compared with $1.6 billion and $5.75 a year earlier. Adjusted EBITDA was $2.54 billion, against $2.29 billion in the third quarter of 2025. The company said its third-quarter result was ahead of its guidance, which it attributed to strong close-in demand and timing-related cost savings.
Net yields, a non-GAAP measure, rose 0.6% in constant currency and 0.9% as reported. Capacity grew 8%, and the company carried 2.7 million passengers, up 9%. Occupancy was 112.4%, compared with 112.1% a year earlier.
Guidance
Royal Caribbean raised its full-year 2026 outlook. It now expects adjusted earnings per share of $17.85 to $17.95, and net yields of about 2.7% as reported or about 2.1% in constant currency. It expects capacity growth of 6.6% for the year. The release does not state the previous full-year figure.
For the fourth quarter, the company guided to adjusted earnings per share of $3.48 to $3.58, with net yields up 4.4% to 4.9% as reported, or 4.2% to 4.7% in constant currency, compared with the fourth quarter of 2025.
Bookings
The release said booking volumes rose in the mid-teens across major channels since the previous earnings call. Chairman and chief executive Jason Liberty said bookings for 2027 are pacing ahead of historical levels at higher rates, while noting that it is still early.
Why It Matters
In our view, the quarter shows two different stories in one release. Capacity, passenger numbers and earnings all rose, but net yields rose by less than 1%, so much of the growth came from more capacity and more guests rather than from higher net yields, which measure net revenue per available passenger cruise day. The fourth-quarter yield guidance is considerably higher than the third-quarter result, and the company’s own reasons for that, which include an easier comparison and the timing of dry docks, are worth weighing alongside its booking commentary.
Leave a Reply