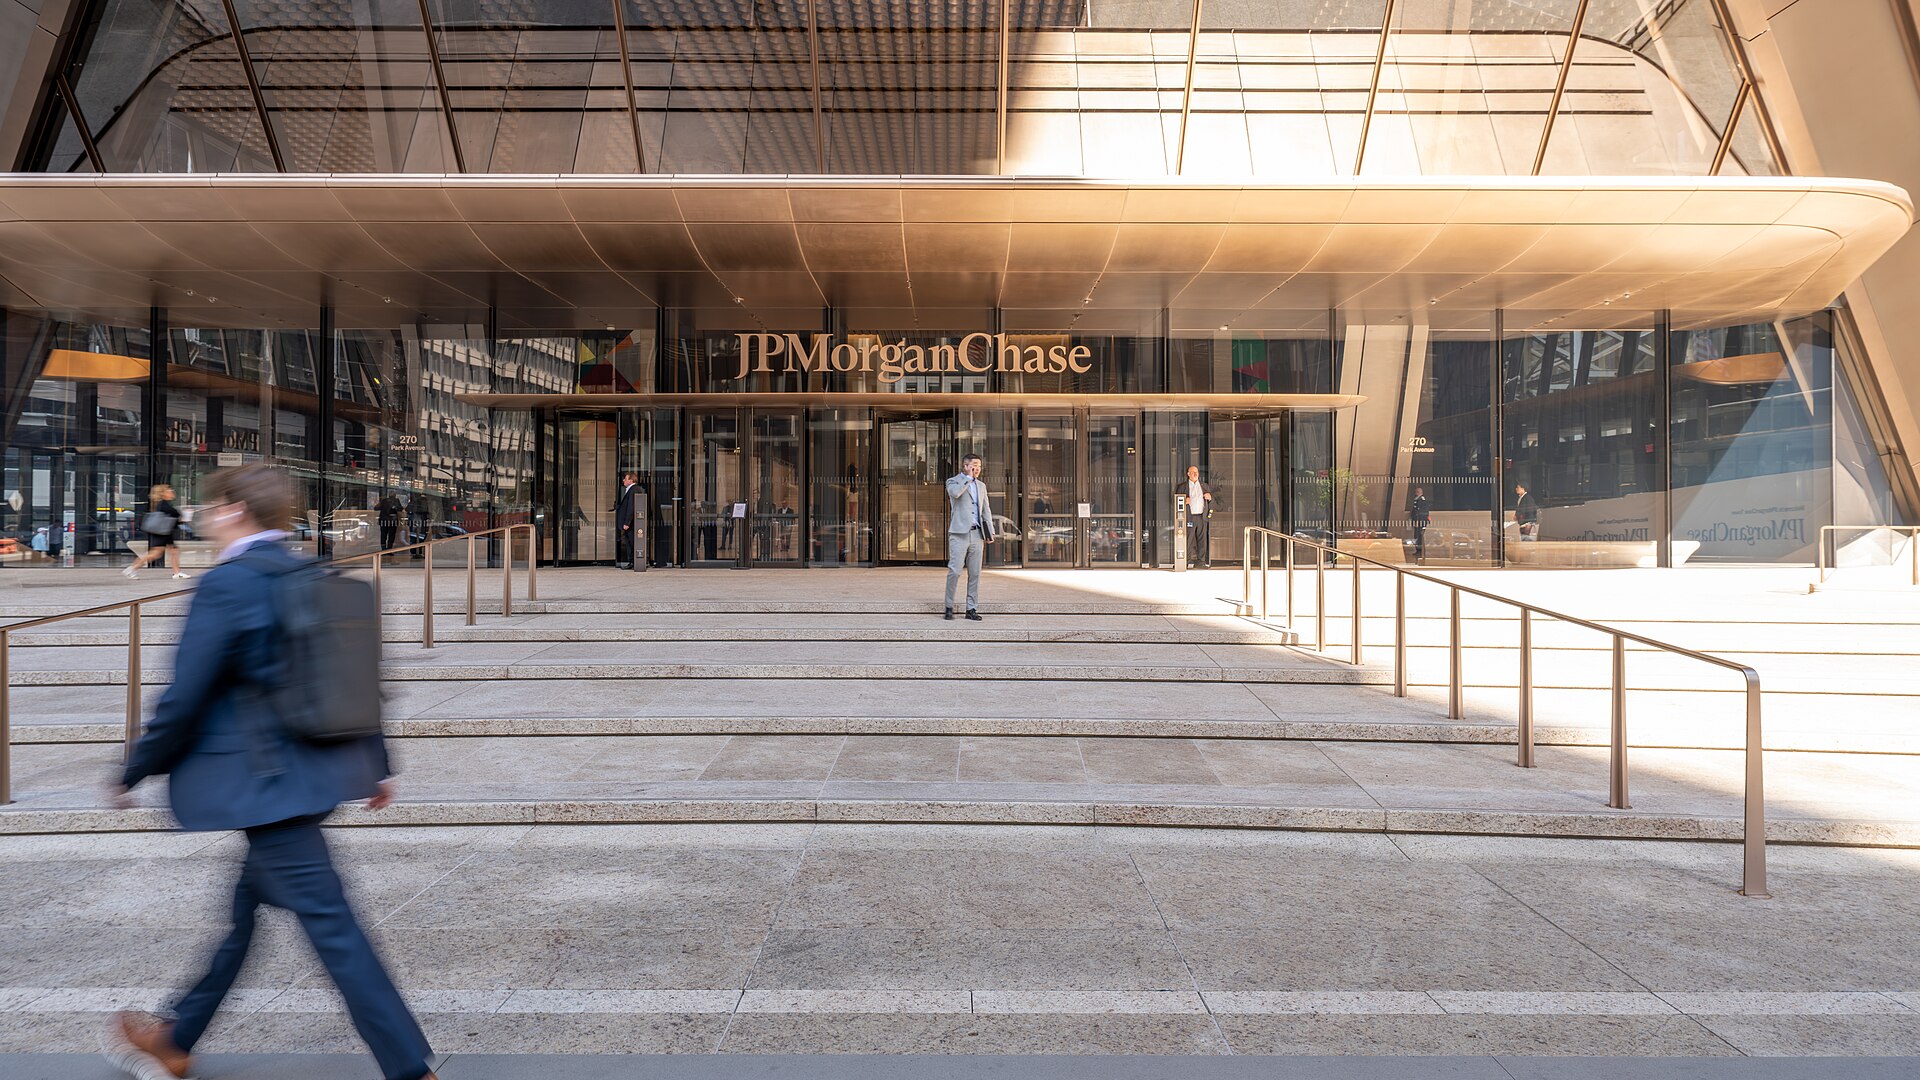
JPMorgan Chase reported third-quarter 2026 net income of $15.3 billion, up 6% from a year earlier, in an earnings release filed with the US Securities and Exchange Commission on 13 October 2026. According to the release, net income was 28% lower than in the second quarter, when it was $21.2 billion. Reported net revenue rose 8% from the third quarter of 2025 to $50.2 billion.
What Moved the Numbers
Costs grew faster than revenue. Noninterest expense rose 12% to $27.3 billion, which the bank attributed predominantly to higher compensation, brokerage expense, distribution fees, marketing and technology spending. The provision for credit losses fell 19% to $2.7 billion, made up of $2.2 billion of net charge-offs and a $539 million net reserve build.
The quarter also included what the bank labelled a significant item: $658 million of net investment securities losses in the Corporate segment, which it said reduced earnings per share by $0.18. Excluding that item, the bank said net income would have been $15.8 billion, or $5.75 per share, against the reported $5.57. The Corporate segment recorded a net loss of $455 million, compared with net income of $825 million a year earlier and $4.2 billion in the second quarter.
The Business Lines
In the commercial and investment bank, net income rose 20% to $8.2 billion on net revenue of $22.7 billion, up 14%. Consumer and community banking net income rose 13% to $5.7 billion. Asset and wealth management posted net income of $1.8 billion, up 11%, with net revenue up 14%. The bank said assets under management rose 13% to $5.2 trillion and client assets rose 15% to $7.9 trillion, driven by continued net inflows and higher market levels.
On capital, the release gives a standardised Common Equity Tier 1 ratio of 13.9%. Chairman and chief executive Jamie Dimon said the bank reduced share repurchases during the quarter, and the release lists $664 million of net common stock repurchases and a common dividend of $1.65 per share. Dimon also said the bank remains “prepared for a wide range of outcomes”, pointing to deficits, inflation and geopolitical conditions.
Why It Matters
JPMorgan operates consumer, corporate and wealth businesses, so its quarterly figures give a broad view of how a large United States bank is performing. This quarter’s picture is mixed rather than weak: revenue and client assets grew, and the commercial and investment bank posted a double-digit rise in profit, but expenses rose faster than revenue and a one-off securities loss lowered the headline figure. The fall from the second quarter should be read with care, because the Corporate segment swung from a $4.2 billion profit in that quarter to a loss in this one, according to the release.
Leave a Reply